Coyyn Com: Digital Finance, Business and Its Key Topics
- November 1, 2026
- 0
Money has always influenced how people work, build businesses, and plan their futures, but the systems used to manage it are changing considerably. A freelancer can now work
Money has always influenced how people work, build businesses, and plan their futures, but the systems used to manage it are changing considerably. A freelancer can now work
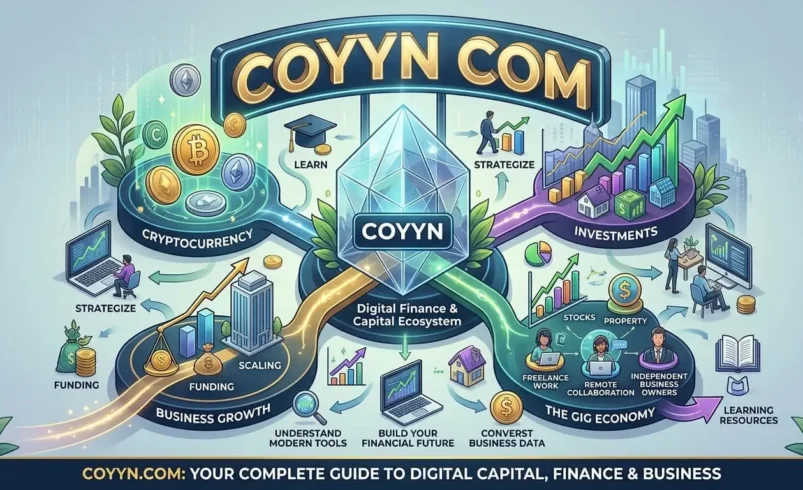
Money has always influenced how people work, build businesses, and plan their futures, but the systems used to manage it are changing considerably. A freelancer can now work with customers in different countries, an entrepreneur can explore funding opportunities online, and an individual can access financial services without depending entirely on a traditional bank branch. Behind these developments is a growing relationship between technology and economic activity that deserves closer attention.
Coyyn Com is associated with this changing financial environment through its coverage of digital banking, cryptocurrency, financial technology, business development, investments, and the gig economy. These subjects may appear different at first, but they share an important connection: each reflects how individuals and organizations interact with money in an increasingly digital world.
Understanding Coyyn Com involves more than identifying its general subject matter. Readers also need to understand the website’s informational purpose, the financial concepts connected with its content, and the practical situations in which those concepts become relevant. A discussion about digital banking, for example, becomes more meaningful when considered alongside online payments, international business, and personal financial management.
This article examines Coyyn Com through that wider perspective. It explores the financial and technological ideas associated with the website, explains their practical applications, considers their limitations, and discusses how readers can approach digital finance information responsibly. It also distinguishes educational publishing from actual financial services, an important difference when evaluating websites that discuss banking, cryptocurrency, and investments.
| Fact | Details |
|---|---|
| Website Name | Coyyn Com |
| Website Address | https://coyyn.com/ |
| Website Type | Digital finance and informational publishing website |
| Main Subject | Finance, technology, business, and the digital economy |
| Core Topics | Digital banking, cryptocurrency, investments, and business funding |
| Related Subjects | Gig economy, private equity, digital capital, and financial literacy |
| Content Format | Online informational articles and educational material |
| Intended Audience | Entrepreneurs, freelancers, investors, and general readers |
| Main Focus | Explaining developments in digital finance and modern business |
| Banking Institution | Not established as a bank |
| Cryptocurrency Exchange | Not established as an exchange |
| Personalized Financial Advice | Not established as a personalized advisory service |
| Ownership Details | Require independent verification |
Coyyn Com is an informational website associated with subjects that connect finance, technology, entrepreneurship, and the digital economy. Its editorial direction brings together different areas of modern economic activity, allowing readers to explore subjects such as cryptocurrency, banking, financial technology, business funding, and independent employment.
The significance of this combination becomes clearer when considering how financial decisions have changed. In the past, an individual interested in banking might primarily have needed to understand savings accounts, loans, and traditional financial institutions. Today, that same person may also encounter digital wallets, online payment providers, international transfers, and cryptocurrency-related services.
Businesses face similar changes. Entrepreneurs increasingly depend on digital payment systems, online accounting applications, financial management software, and different forms of funding. Understanding one part of this environment often requires some knowledge of another.
Coyyn’s subject coverage relates to these overlapping developments. Rather than approaching financial technology as an isolated industry, its broader editorial focus connects financial services with the people and organizations that use them.
One important distinction deserves attention from the beginning. A website discussing banking, investments, or cryptocurrency is not automatically a provider of those services.
An informational publication generally helps readers understand financial concepts through written explanations, articles, and educational discussions. A regulated bank, on the other hand, operates financial accounts and provides services under the applicable laws of its jurisdiction. A cryptocurrency exchange has a different purpose, usually involving the buying, selling, or trading of digital assets.
These activities should not be confused.
Coyyn’s informational positioning means readers should approach its financial coverage as educational material rather than assuming that visiting the website provides access to banking accounts, investment management, or cryptocurrency transactions. Anyone considering a financial product should independently verify the actual provider, its terms, and its regulatory status.
The name Coyyn may attract people who have encountered the website through an article, an online recommendation, or a discussion about digital finance.
Some visitors may be looking for information about cryptocurrency, while others may want to understand the website’s connection with business or financial technology. There are also readers who simply want to establish whether Coyyn is a publication, a financial platform, or a service provider.
These questions are understandable because financial terminology is frequently used by different types of online businesses. A website may discuss digital currencies without operating an exchange, just as a publication covering business funding does not necessarily provide loans.
Identifying the website’s actual purpose is therefore a sensible first step.
Finance and technology have become closely connected because modern economic activity increasingly depends on digital infrastructure. People use online systems to transfer money, receive salaries, manage accounts, purchase products, and conduct business across geographical boundaries.
This transformation involves much more than replacing physical banking branches with mobile applications. It changes how transactions are processed, how financial information is stored, how businesses manage payments, and how consumers interact with financial institutions.
Traditional banking relied heavily on physical branches and direct interactions between customers and banking employees. Customers often visited branches to transfer funds, obtain account information, deposit money, or discuss financial products.
Digital banking has made many of these activities accessible through online systems. Depending on the provider, customers may be able to check balances, transfer funds, pay bills, review transactions, and manage certain financial products through websites or mobile applications.
This development has made routine financial management more convenient, particularly for people who cannot easily visit physical branches.
However, digital banking also introduces new considerations. Customers must understand authentication methods, password security, account recovery procedures, transaction verification, and the responsibilities associated with protecting personal financial information.
Coyyn’s coverage of banking and financial technology connects with these changes by providing a subject area for understanding how digital financial services operate.
Financial technology, commonly called fintech, includes digital systems and services designed to support or improve financial activities.
Its applications extend beyond banking. Payment processors help businesses accept electronic payments, accounting platforms organize financial records, lending technology supports certain financing processes, and digital wallets allow users to manage supported forms of electronic value.
For small businesses, these tools can reduce the need to manage every financial activity manually.
Consider a business selling products through an online store. It may use a payment gateway to process customer transactions, accounting software to record income and expenses, and financial dashboards to understand its cash position.
These systems perform different functions, but together they create a more organized financial workflow.
The important point is that technology should solve a practical problem. A business does not necessarily benefit from adopting every new financial application. It should first understand its requirements, operating costs, security needs, and available alternatives.
Cryptocurrency is one of the most recognizable subjects associated with the modern digital economy. It has attracted attention from technology enthusiasts, investors, entrepreneurs, and people interested in alternative financial systems.
Coyyn’s cryptocurrency-related coverage connects with a subject that combines computer science, economics, financial markets, and digital ownership.
Cryptocurrency refers to digital assets that generally use cryptographic techniques and distributed ledger systems to support transactions and record ownership.
Many cryptocurrencies operate through blockchain networks. A blockchain is a type of distributed database in which transactions are recorded in connected blocks according to the rules of the network.
Unlike conventional financial systems, which commonly depend on centralized institutions to maintain transaction records, public blockchain networks can allow multiple participants to verify transactions.
This does not mean every cryptocurrency operates identically. Different networks use different technical designs, transaction mechanisms, security arrangements, and governance structures.
For beginners, understanding these differences is more useful than assuming that all digital currencies perform the same function.
Bitcoin and Ethereum are two widely recognized names within the cryptocurrency ecosystem, but their underlying purposes are not identical.
Bitcoin is primarily associated with decentralized digital money and a monetary system designed around a limited supply. Its network allows participants to transfer bitcoin without depending on a conventional central bank to issue the asset.
Ethereum provides a programmable blockchain environment. Developers can build decentralized applications and smart contracts that execute according to predefined conditions.
These differences help explain why cryptocurrency is a broader technological and financial category rather than a single product.
Readers interested in the subject can explore the background of Bitcoin on Wikipedia to understand its origins and basic design.
Owning cryptocurrency involves more than purchasing a digital asset. Users also need to understand how access to those assets is controlled.
Cryptocurrency wallets interact with blockchain networks through cryptographic keys. A private key or recovery phrase can provide control over associated assets, making its protection extremely important.
If a user loses access to the relevant credentials, recovering the assets may be difficult or impossible, depending on the wallet arrangement.
Security risks also include phishing websites, fraudulent applications, impersonation attempts, malicious software, and unauthorized access.
Anyone exploring cryptocurrency should understand wallet security before transferring meaningful amounts of money. The appearance of a professional website or an attractive investment opportunity does not establish that a digital asset or service is legitimate.
Cryptocurrency markets can experience substantial price movements. Asset values may change because of market sentiment, liquidity, technological developments, regulatory decisions, and broader economic conditions.
There are also risks associated with project management, software vulnerabilities, exchange failures, and fraudulent investment schemes.
For these reasons, learning about cryptocurrency should begin with understanding how the technology works and what can go wrong. Readers should avoid interpreting educational discussions as promises of financial returns.
Banking remains an essential part of economic life, but customers increasingly expect financial services to be accessible through digital channels.
This development has influenced both established banks and newer financial technology companies. Many institutions now offer online services, while some providers operate primarily through digital platforms.
Digital banking can simplify routine financial activities by making account information and supported transactions available through connected devices.
A customer may use online banking to review recent payments, transfer money, pay bills, or monitor account activity. Some institutions also offer budgeting features, spending summaries, and automated notifications.
These functions can help people understand their financial position without manually reviewing every transaction.
For someone managing several financial responsibilities, organized digital records can make it easier to recognize spending patterns and identify unusual activity.
Nevertheless, users should understand the protection offered by their financial institution and follow its security recommendations.
Businesses also benefit from digital financial systems.
A company may need to receive customer payments, pay suppliers, manage payroll, review cash flow, and organize invoices. Digital banking and accounting systems can help bring these activities into a more manageable process.
For an online business, payment timing is especially important. Revenue recorded in a sales dashboard does not necessarily mean that the money is immediately available in the company’s bank account.
Payment processing delays, refunds, transaction fees, and settlement schedules can all influence working capital.
Understanding these details helps business owners avoid confusing sales figures with available cash.
Convenient financial access creates responsibilities for customers and service providers.
Weak passwords, reused login credentials, phishing messages, and compromised devices can expose financial accounts to unauthorized access.
Users should enable appropriate authentication methods, keep devices updated, verify transaction notifications, and avoid accessing sensitive accounts through suspicious links.
A digital banking provider should also be evaluated according to its regulatory status, privacy practices, customer support, and security arrangements.
Capital is one of the foundations of business development. Companies need financial resources to begin operations, develop products, acquire equipment, recruit employees, and expand into new markets.
Coyyn’s connection with digital capital and business funding introduces another important dimension of the modern economy.
A business can have a strong product idea and a clear customer base but still struggle because it lacks sufficient financial resources.
Capital provides the money required to turn plans into operating activities.
For example, a small manufacturing company may need equipment and inventory before it can generate revenue. A software business may need developers, infrastructure, and marketing resources before launching its product.
The amount and type of capital required depend on the business model, operating costs, growth expectations, and financial circumstances.
Two important business funding approaches are debt financing and equity financing.
Debt financing involves borrowing money that must generally be repaid according to agreed conditions. The agreement may include interest, repayment schedules, collateral requirements, and other obligations.
Equity financing involves providing an ownership interest in exchange for investment. The investor may receive a share of the business and potentially participate in certain decisions or future financial benefits.
Neither approach is universally better.
A business owner who borrows money retains ownership but accepts repayment responsibilities. An entrepreneur accepting equity investment may receive resources for growth but share ownership and potentially some control.
Understanding these differences is important before accepting funding.
Private equity and venture capital are investment approaches that involve providing capital to businesses in exchange for ownership interests or other agreed financial arrangements.
Venture capital commonly focuses on businesses with growth potential, particularly early-stage companies developing products, technology, or scalable business models.
Private equity can involve investment in more established businesses and may include different ownership, restructuring, or expansion strategies.
These investment models require detailed evaluation. Investors consider the company’s business model, management, market opportunity, financial position, and potential risks.
Entrepreneurs should also understand valuation, investor rights, ownership dilution, and contractual obligations before entering an investment arrangement.
Crowdfunding offers another way for individuals or businesses to obtain financial support from a larger group of contributors.
Different crowdfunding models have different structures. Some involve donations, others provide rewards, and certain arrangements involve loans or equity participation.
A business considering crowdfunding should understand the platform’s fees, campaign requirements, legal obligations, and responsibilities toward contributors.
The availability of funding does not automatically establish that a particular campaign or investment arrangement is appropriate.
The relationship between digital finance and employment becomes particularly visible in the gig economy.
Independent workers increasingly provide services through digital marketplaces, professional networks, and direct client relationships. Their work may include writing, graphic design, programming, consulting, marketing, delivery services, and many other activities.
This employment model offers flexibility, but it also changes how people manage income and financial responsibilities.
Unlike traditional employees who may receive a regular salary, freelancers and independent contractors often earn money through individual projects, hourly agreements, or service contracts.
Their income can fluctuate depending on client demand, project availability, pricing, and payment arrangements.
A freelancer may complete several projects in one month and experience a quieter period in the next.
This makes financial planning particularly important.
Independent professionals need to consider operating expenses, taxes, savings, equipment costs, and the possibility of delayed payments.
Remote work has created opportunities for professionals to serve clients in different countries.
A designer in one country may work with a company located thousands of kilometres away. A writer may receive payments from multiple international customers, while a developer may participate in a project managed by an overseas business.
These arrangements create questions about currency conversion, transaction fees, payment processing, and financial documentation.
A freelancer should understand the available payment methods and the requirements associated with each provider.
It is also important to establish clear agreements about payment deadlines, project scope, revisions, and ownership of completed work.
Flexibility does not necessarily mean financial security.
Freelancers may need to manage periods without paid projects, unexpected expenses, and inconsistent customer payments.
Maintaining financial records, setting aside money for taxes, creating an emergency reserve, and separating business expenses from personal spending can help make independent work more manageable.
Coyyn’s gig economy coverage is relevant to these questions because modern employment increasingly involves digital financial arrangements rather than only conventional salary systems.
One of the most useful ways to understand Coyyn’s broad subject coverage is to examine how different financial concepts interact in practical situations.
Imagine an entrepreneur launching an online business. The first challenge may be developing a product and identifying potential customers. Once the business begins operating, the owner needs to accept payments, track expenses, manage suppliers, and maintain financial records.
If the business grows, additional capital may become necessary. The owner may consider a business loan, external investment, or another financing arrangement.
If customers are located internationally, currency conversion and cross-border payment processing may become relevant.
Each decision connects to a different area of digital finance, but all contribute to the same business objective.
The same relationship applies to independent professionals. A freelancer needs clients, contracts, payment arrangements, budgeting methods, and an understanding of financial obligations.
This interconnected approach explains why banking, technology, business funding, and independent employment are increasingly discussed together.
Coyyn’s financial and business subject areas may appeal to several audiences, depending on their interests and the information they need.
Entrepreneurs frequently face questions about funding, operating expenses, customer payments, financial planning, and business technology.
Understanding these subjects can help them evaluate different opportunities and identify potential challenges before making commitments.
A startup founder exploring investment, for example, may benefit from learning about equity dilution, company valuation, and investor agreements before negotiating with potential funding partners.
Freelancers often work with customers beyond their immediate geographical areas. They may need to understand international payments, transaction fees, currency conversion, and financial recordkeeping.
Information about the gig economy and digital banking can provide useful background for managing these responsibilities.
Students and beginners may use informational articles to understand concepts that they have not encountered before.
Terms such as venture capital, stablecoins, blockchain, and private equity can initially appear complicated. Clear introductory explanations can make these subjects easier to approach.
However, educational articles should complement formal learning rather than replace academic materials or professional training.
People interested in technology may want to understand how digital systems influence financial services.
Payment infrastructure, blockchain networks, digital identity, automated financial processes, and online business applications provide several areas for exploration.
Investment-related information may help readers understand financial terminology, different asset classes, and the relationship between risk and potential returns.
However, general educational material cannot determine whether a particular investment is appropriate for an individual’s circumstances.
Financial literacy involves understanding how money works and using that knowledge to make informed financial decisions.
It includes budgeting, saving, borrowing, investing, understanding financial products, and recognizing potential risks.
Digital financial services have made financial literacy even more important because people can encounter complicated products and transactions through websites and mobile applications.
A basic understanding of income and expenses provides the foundation for financial management.
Individuals should know how much money they receive, what they spend, and which expenses are essential or discretionary.
This becomes especially important for freelancers and business owners whose income may fluctuate.
Borrowing money involves more than looking at the amount being offered.
Interest rates, fees, repayment schedules, penalties, and the total amount payable all influence the actual cost of a loan.
A person considering financing should examine the complete agreement rather than relying on an advertised monthly payment.
Every investment involves some form of risk.
Different assets have different levels of volatility, liquidity, and potential loss. Investors should understand these characteristics before committing money.
Financial literacy does not guarantee successful investment decisions, but it can help people recognize unrealistic promises and ask better questions.
Digital financial activity requires careful protection of personal information.
Users should understand how passwords, authentication systems, private keys, and transaction confirmations work.
They should also recognize phishing attempts and avoid sharing confidential information with unverified websites or individuals.
The potential value of a financial information website depends on the quality, clarity, and relevance of its material.
Coyyn’s broad subject coverage creates opportunities for readers to explore different parts of the digital economy, but that breadth also makes careful evaluation important.
A multi-topic financial publication can introduce readers to subjects they might otherwise approach separately.
Someone learning about freelancing may also become interested in international payments and budgeting. A business owner exploring capital may discover information about digital banking and financial technology.
This connected approach can help readers develop a broader understanding of modern economic activity.
Another potential advantage is accessibility. Introductory explanations can make technical subjects easier to understand, particularly for readers who are new to finance or business.
The website’s subject diversity may also support independent learning by providing different starting points for further investigation.
Broad subject coverage does not automatically demonstrate specialist expertise.
An article about cryptocurrency requires a different level of technical understanding from an article about entrepreneurship or business funding. Health, taxation, and legal subjects introduce additional responsibilities when they are discussed.
Readers should therefore evaluate individual articles instead of assuming that every category offers the same level of expertise.
Another consideration is the changing nature of financial information. An explanation of a particular payment service, investment product, or regulation may become outdated.
Publication dates, author credentials, and supporting information should be considered when assessing the usefulness of an article.
Coyyn’s association with digital banking and cryptocurrency may lead some visitors to assume that it provides financial services directly.
However, discussing a financial product is different from operating that product.
A bank provides financial services such as accounts, deposits, transfers, and other regulated activities under the laws applicable to its operations.
A cryptocurrency exchange generally provides a platform for users to trade digital assets, subject to its business model and regulatory requirements.
An informational website has a different purpose. It publishes material that helps readers understand these industries and their terminology.
Coyyn’s informational positioning should therefore not be interpreted as proof that it operates bank accounts, accepts customer deposits, manages investments, or provides cryptocurrency trading.
Anyone considering a service associated with the Coyyn name should verify the exact provider, its legal identity, regulatory position, and contractual terms before sharing money or personal information.
Readers should approach financial content with a level of attention appropriate to the subject.
A general explanation of a financial term may require relatively little additional investigation. An article discussing a specific investment, banking product, or financial regulation requires much more careful verification.
Start by identifying the purpose of the article. Is it introducing a concept, reviewing a product, explaining a financial process, or promoting a particular service?
Next, examine the information supporting its claims. Important statements should be understandable and capable of being checked independently.
Author information also matters. When an article discusses specialist financial subjects, relevant experience and professional knowledge can help readers assess its reliability.
Publication dates deserve attention because financial regulations, digital services, and market conditions change.
Finally, consider the difference between general educational material and personalized recommendations. A website cannot determine whether an investment or loan is suitable simply by publishing an article about it.
These habits allow readers to use informational content without placing unnecessary confidence in any single online resource.
The relationship between financial services and technology is likely to remain an important part of economic development.
Digital payments, financial automation, online banking, and data-driven business tools continue to influence how individuals and organizations manage their money.
Artificial intelligence may also support financial administration through automated record organization, transaction analysis, customer support, and other applications. At the same time, it introduces concerns about data privacy, accuracy, transparency, and accountability.
Blockchain technology may continue developing through applications involving digital ownership, transaction verification, and decentralized financial systems.
The gig economy is also likely to remain relevant as businesses and professionals explore remote collaboration and flexible working arrangements.
However, technological development does not guarantee that every new financial product will succeed. Some innovations may become widely adopted, while others may face technical, regulatory, or commercial challenges.
For an informational publication such as Coyyn, these developments create opportunities to explain new concepts and help readers understand their practical implications.
The most useful discussions will be those that examine both possibilities and limitations rather than presenting every technological development as an automatic improvement.
Coyyn Com is an informational website associated with digital finance, business, financial technology, cryptocurrency, and the modern economy. Its subject areas include digital banking, investments, business funding, digital capital, and the gig economy. It provides a starting point for readers interested in understanding how financial and technological developments influence everyday economic activity.
Coyyn’s subject coverage includes digital banking, cryptocurrency, financial technology, private equity, business development, digital capital, investments, and independent employment. Related discussions may also address stablecoins, financial literacy, and the changing structure of the digital economy. The exact availability of individual topics should be checked on the current website.
Coyyn’s informational identity should not be confused with a cryptocurrency exchange. Discussing Bitcoin, Ethereum, blockchain, or digital assets does not establish that a website provides cryptocurrency trading services. Anyone considering a trading service associated with the Coyyn name should independently verify the provider and its regulatory status.
The website’s coverage of digital banking does not establish it as a banking institution. Readers looking for actual bank accounts, deposits, or payment services should approach appropriately regulated financial providers and review their terms and protections.
Its broad financial and business subject areas can provide introductory material for people unfamiliar with modern financial concepts. Beginners may use explanations of cryptocurrency, digital banking, and business funding to develop basic knowledge. Important financial decisions should still involve additional research and, where appropriate, professional advice.
Coyyn’s informational positioning should not be interpreted as a personalized financial advisory service. General articles cannot account for every individual’s income, obligations, financial goals, or risk tolerance. Readers should treat educational discussions as background information rather than personal instructions to invest, borrow, or purchase financial products.
The gig economy is one of the subjects associated with Coyyn’s broader financial and business coverage. It involves freelancers, independent contractors, consultants, and other professionals who earn income through project-based or flexible working arrangements. This subject connects with digital payments, financial planning, and the changing nature of employment.
Digital capital generally refers to financial resources and capital-related activities connected with digital business environments. The term can relate to online funding systems, technology-driven financial services, and the financial resources businesses use to develop digital operations. Its precise meaning depends on the context in which it is used.
Digital money is a broad term for monetary value represented or transferred electronically. Cryptocurrency is a particular category of digital asset that generally uses cryptographic techniques and distributed ledger technology. Conventional bank balances, electronic payment balances, and cryptocurrencies can all exist in digital form, but they do not operate under identical systems.
No. Informational websites can help readers understand financial concepts, but they should not be the only basis for important financial decisions. Investments, loans, taxation, banking arrangements, and cryptocurrency transactions require independent verification. Depending on the circumstances, consulting a qualified financial or legal professional may also be appropriate.
Coyyn Com is associated with a collection of subjects that increasingly influence how people earn, manage, transfer, and invest money. Digital banking, cryptocurrency, financial technology, business funding, and independent employment are not isolated developments. They are connected parts of an economic environment in which technology plays an increasingly important role.
The website’s broad informational direction offers readers different ways to explore these subjects. Entrepreneurs can investigate business funding and digital tools, freelancers can learn about the financial responsibilities of independent work, and beginners can develop a basic understanding of cryptocurrency and modern banking systems.
Nevertheless, understanding the distinction between educational information and actual financial services remains essential. A website discussing cryptocurrency is not automatically an exchange, and an article explaining banking technology does not establish that its publisher operates a regulated financial institution.
Readers should evaluate individual articles, verify important financial claims, and consider the date and context of the information they encounter.
Ultimately, the real value of exploring Coyyn Com lies in understanding the wider relationship between money, technology, and business. Developing financial knowledge, asking informed questions, and recognizing potential risks can help readers navigate an increasingly digital economy with greater confidence and better judgment.
For More Visits: Worldmagazine